Tax case at The Royal Theatre raises questions about the conditions for stage artists
The Danish Artists’ Union has had cases where members have been caught in the Royal Theatre’s practice regarding guest artists. Most recently, the Tax Agency has asked the theatre to make amends, and this is in line with the union’s assessment: The employer cannot simply decide what employment form an artist must have.
By Julie Westh Nielsen
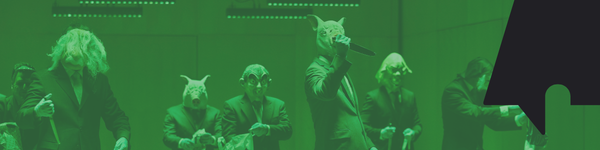
A member of the Danish Artists’ Association had problems with, among other things, the right to maternity leave in a case concerning the Royal Theatre’s practice of paying guest artists as independent contractors.
The case raised a fundamental question: who decides whether an artist works as an employee or as an independent contractor. The theater artist had problems with the right to maternity leave because the Royal Theatre decided to pay the artist as an independent contractor. This was reported by the federation’s deputy head, Sara Indrio, to Culture Monitor, which brought the story on September 23rd.
But employers cannot freely choose how wages are paid. It depends on how the artist and employer arrange work in practice, says Sara Indrio to Kulturmonitor:
According to the head of the department, it is not irrelevant whether the payment is reported as self-employment income or employee income, because that determines which rights the law grants in terms of maternity leave, illness, and the like.
The case is not settled
The Danish Tax Agency has urged The Royal Theatre to treat guest employees who, after a specific assessment, are considered to be employees as such. The theatre has appealed against the instruction, but no clarification of the appeal has been published.
This does not mean that all guest artists must automatically be considered employees. The Tax Agency assesses the actual circumstances in each case. This may include, among other things, whether the employer instructs the artist as to who bears expenses and financial risks, and how freely the artist can organize their work.
Disagreement over the consequences for the industry
Danish Scenekunst is concerned about the consequences of the Tax Administration’s assessment. Director Peter Mark Lundberg emphasizes that the organization advocates for fair terms, but is concerned that a changed tax policy could make it difficult for theaters to attract international artists for short-term engagements.
In a Subsequent discussion contributions The Danish Scenographers and Danish Scene Instructors also point out that changed tax practices could have consequences for the performing arts industry. They believe, at the same time, that the industry’s need for flexibility should not become a burden that artists themselves have to bear.
Are you unsure about your contract?
If you are offered a B-fee or are unsure of the status your work gives you, you can contact the Danish Artist Association before entering into the agreement. The association offers advice on contracts and tax advice on, among other things, the status of an employee, honorarium recipient or self-employed person.